
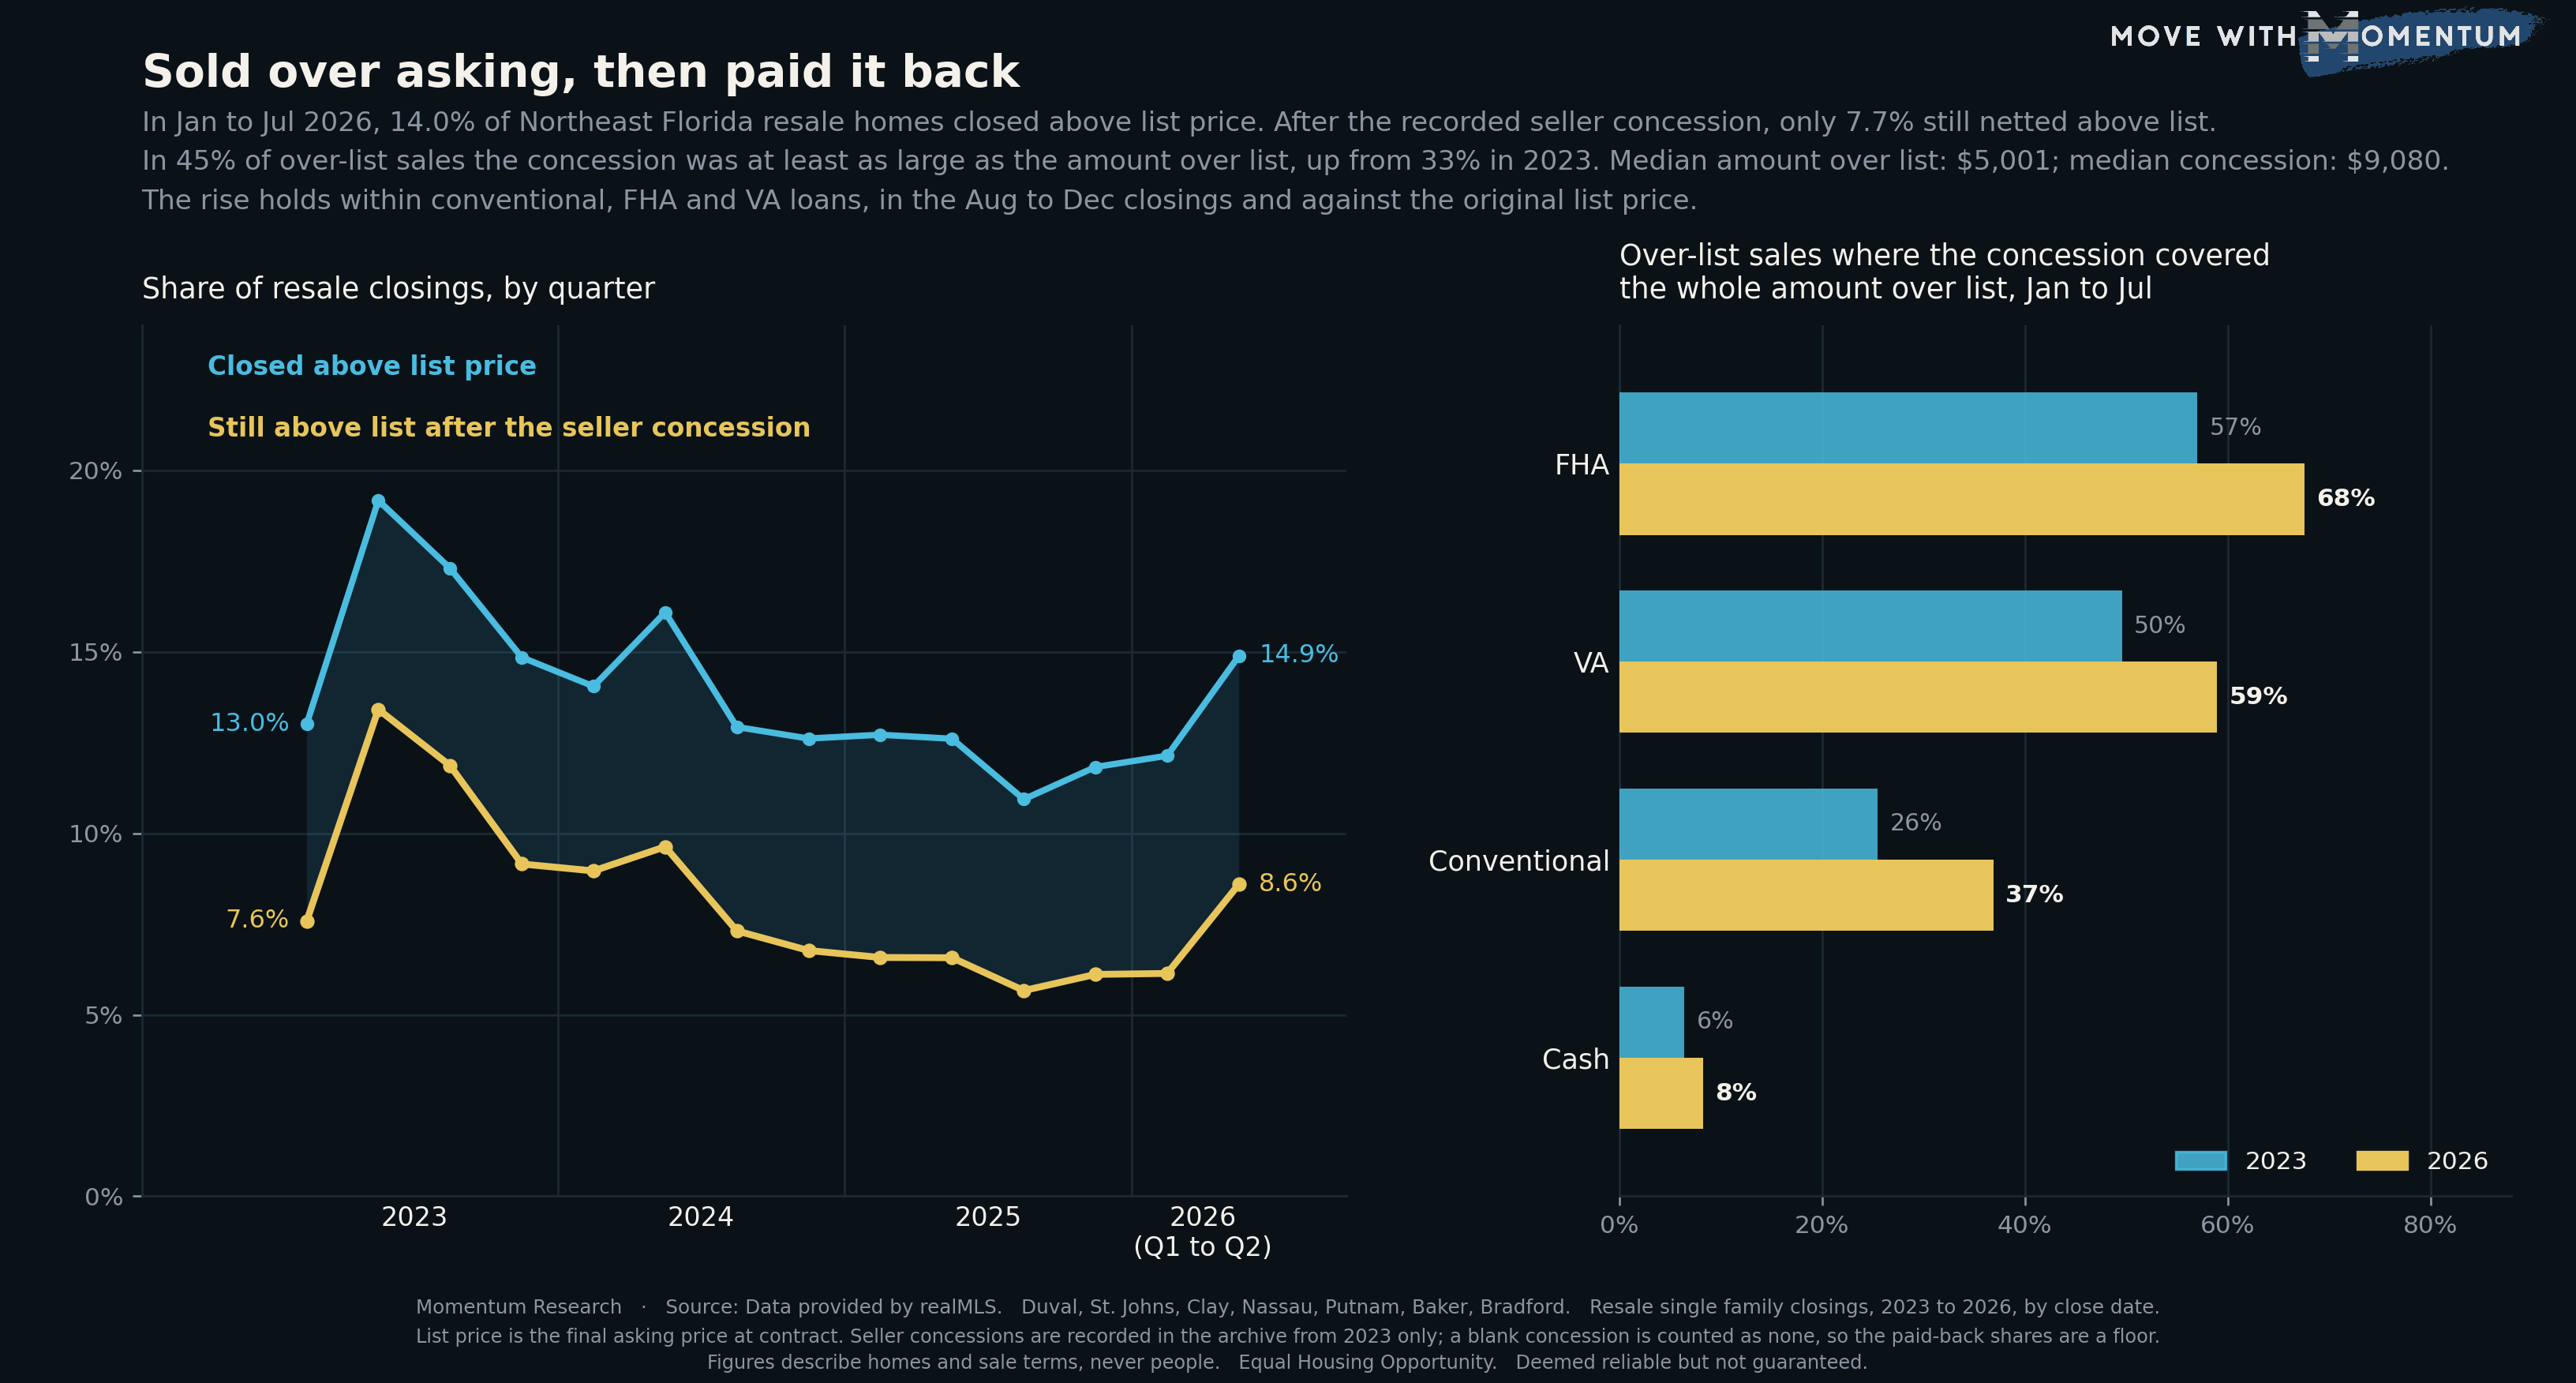
A sale "over asking" still reads as a win on the closing report. The records show how often it is one. In January to July 2026, 14.0% of Northeast Florida resale homes closed above their list price. Subtract the seller concession recorded on the same sale and only 7.7% still netted above list. In 45% of the over-list sales, the concession was at least as large as the amount over list, up from 33% in the same months of 2023.
That matters for anyone reading comparable sales. A close price above list can describe a bidding situation, or it can describe a price that was raised so the seller could pay part of the buyer's closing costs. The close price alone does not say which.
How the over-asking math was measured
The method takes resale single family closings in the seven counties realMLS is authoritative for, 2023 through 2026. A sale counts as over asking when the close price is above the list price in effect when the contract was signed. The amount over list is the close price minus that list price. A sale counts as paid back when the recorded seller concession is at least that amount, and as net over list when the close price minus the concession is still above list.
Seller concessions are only in the archive from 2023, so the series starts there; the blank field before 2023 is an archive limit, not a zero. A blank concession on a 2023 or later record is counted as none, which means the paid-back shares here are a floor. Annual figures use the same January to July window in every year because the archive runs through August 13, 2026 and July is the last complete month. The quarterly chart uses complete quarters only.
Fewer over-list sales, and more of them handed back
The share of resale closings above list peaked at 19.2% in the second quarter of 2023, slid to about 11% in 2025 and was back to 14.9% in the second quarter of 2026. The share still above list after the concession followed the same shape at a lower level: 13.4% at the 2023 peak, a 5.7% low in the third quarter of 2025 and 8.6% in the second quarter of 2026. The gap between the two lines is the part of the over-list headline that went back across the table as a seller credit.
Within over-list sales the concession became the norm. In January to July 2023, 52.5% of them carried a recorded concession; in 2026, 62.1% did. The typical amount over list barely moved, $5,100 in 2023 and $5,001 in 2026, while the median concession on those sales rose from $7,000 to $9,080. The paid-back share went from 33.5% (2023) to 38.9% (2024) and 47.4% (2025), and was 45.1% in 2026. The median amount a seller kept above list on an over-list sale, after the concession, fell from about $2,000 to about $500.
Rival explanations we tested
- More FHA and VA buyers. Government-backed loans carry concessions more often, so a shift toward them could create the rise alone. It does not: within each loan type the paid-back share rose, FHA from 57.0% to 67.6%, VA from 49.6% to 59.0% and conventional from 25.5% to 36.9%. Holding the 2023 loan mix fixed, the 2026 figure is 42.8% against 33.7% in 2023. Cash over-list sales were paid back only 6.4% and 8.3% of the time.
- Cheaper homes. The paid-back share rose in every list price fifth, for example from 39.4% to 57.8% in the second fifth and from 13.7% to 19.3% in the top fifth.
- County mix. It rose in Duval (33.5% to 46.9%), St. Johns (19.3% to 28.6%) and Clay (45.0% to 50.7%), the three counties with enough over-list sales to read.
- Partial year. August to December closings give 35.2% in 2023, 45.9% in 2024 and 49.4% in 2025, and full calendar years give 34.1%, 41.3% and 48.1%, in line with the January to July figures.
- Final list versus original list. Measured against the original asking price instead, fewer sales count as over asking (10.7% in 2026), but the paid-back share still rose, from 24.3% in 2023 to 35.8% in 2026.
- New construction. Builder sales are left out of the headline. Measured the same way, their paid-back share rose from 23.8% to 38.9%, so the pattern is not limited to resale.
What this cannot capture: the records show the concession amount, not what it paid for. Some credits cover closing costs, some cover repairs found at inspection, some buy down the rate. It also cannot see sales where a concession was agreed but not entered, which is why the paid-back figures are a floor.
How agents can use this data
- Read comps net of the credit. A comparable that closed $5,000 over list with a $9,000 concession did not sell above list for the seller. Pull the concession field before quoting an over-list comp, the same adjustment covered in our look at seller concessions in Northeast Florida.
- Compare offers on the seller's net. When two offers arrive, the one with the higher price and a credit can net less than a lower clean offer. Put both on a net sheet side by side.
- Expect a credit with government-backed financing. In 2026, 67.6% of FHA and 59.0% of VA over-list sales carried a concession at least as large as the premium, against 36.9% of conventional and 8.3% of cash. Our cash offer discount study shows the same pattern from the other side.
- Set expectations on the headline number. Only 7.7% of 2026 resale closings netted above list after the concession, so a list-price strategy built on a bidding premium should plan for the credit too. Our below-asking price study shows the full range of outcomes.
Whichever way you use the numbers, cite the source: Momentum Research analysis of data provided by realMLS, resale single family closings 2023 through 2026, deemed reliable but not guaranteed.
What this measurement does not do
It does not forecast, value any home or judge any sale. It measures prices, list prices and recorded concessions on homes, never the people buying or selling them, and it should be read alongside a current comparable-sales analysis rather than in place of one.
People also ask
How often do homes sell over asking price in Jacksonville?
In January to July 2026, 14.0% of resale single family homes in the seven Northeast Florida counties realMLS covers closed above their final list price, down from 16.7% in the same months of 2023. After subtracting the recorded seller concession, 7.7% still closed above list, against 11.1% in 2023.
Why would a buyer offer over asking price and ask for closing costs?
A seller credit toward closing costs lowers the cash a buyer needs at the table, and raising the price by a similar amount keeps the seller's net close to the list price. The price still has to be supported by the appraisal for a financed purchase. In the 2026 records, the median over-list sale closed $5,001 above list with a median concession of $9,080 where one was recorded, and in 45% of over-list sales the concession was at least as large as the amount over list.
Does selling over asking mean the seller made more money?
Not always. Across over-list resale sales in January to July 2026, the median amount the seller kept above list, after the concession, was about $500, down from about $2,000 in 2023. Whether a specific sale netted more depends on the concession, the price and the other terms of that contract, so the full settlement figures are the number to compare, not the headline price.
Method and limits
Source: data provided by realMLS. Closed resale single family sales (NewConstructionYN false, PropertySubType Single Family Residence) in the authoritative counties of Duval, St. Johns, Clay, Nassau, Putnam, Baker and Bradford. Records are deduplicated on listing id plus close date; sales under $10,000 or with a close price below half or above one and a half times list are dropped. Seller concessions (ConcessionsAmount) exist in the archive from 2023 only; a blank value on a 2023 or later record is counted as no concession. Annual figures use January through July of every year; the archive ends on August 13, 2026, so July is the last complete month. The quarterly series covers the first quarter of 2023 through the second quarter of 2026.
List price is ListPrice, the asking price in effect when the contract was signed. Over list means close price above list price. Paid back means the recorded concession is at least the close price minus the list price. Net over list means close price minus concession above list price. Financing groups use sales with exactly one recorded financing type. The reweighted figure applies the 2026 paid-back share within FHA, VA, conventional and cash to the 2023 count of over-list sales in each group.
What the concession paid for, appraisal outcomes and contract terms outside the recorded fields are not observed. Cause is not identified.
Related reading on the same archive: how often homes sell below original ask, assumable mortgages in listings, listing description words and the ongoing Jacksonville housing market tracker.
All figures on this page are per Momentum Research analysis of data provided by realMLS and are deemed reliable but not guaranteed. Equal Housing Opportunity.